(Data as of 12 October 2026)
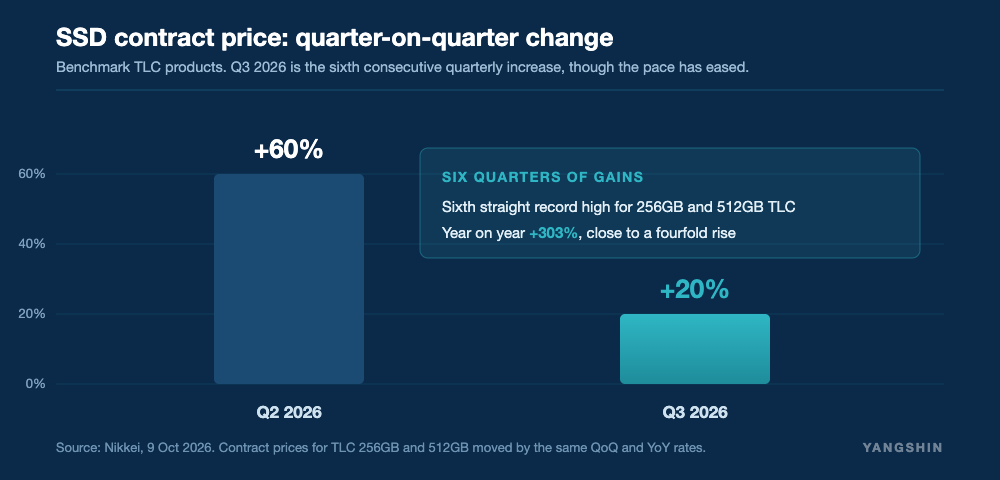
The first hard numbers for the quarter are in. Nikkei reported on 9 October that Q3 2026 contract prices for solid-state drives settled at about USD 134.2 per 256GB TLC drive and USD 252.0 per 512GB drive, both up roughly 20% quarter on quarter — a sixth consecutive quarterly increase and a fresh record high. Year on year both are up 303%, close to a fourfold rise in twelve months.
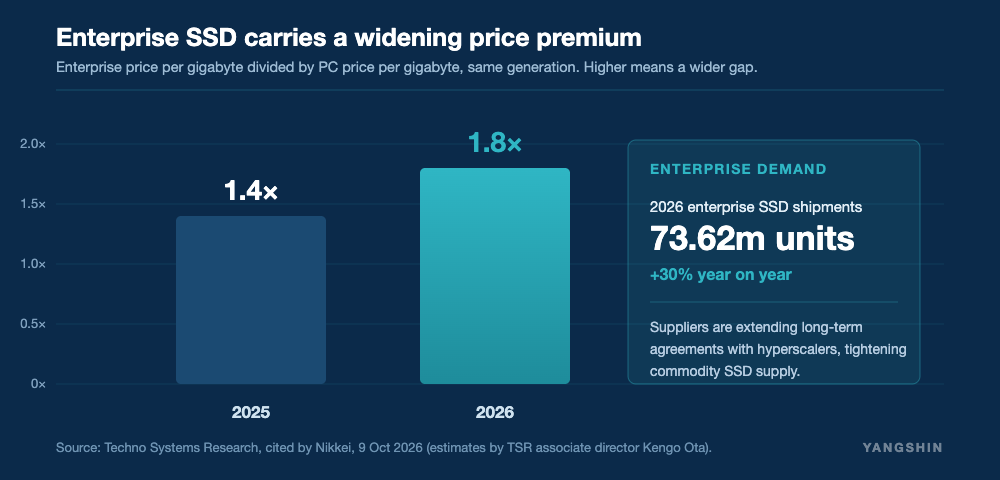
Supply structure is the driver. As hyperscalers keep expanding AI data-centre capacity, Techno Systems Research expects enterprise SSD shipments to reach 73.62 million units in 2026, up about 30% year on year. Suppliers are extending long-term agreements with cloud customers, which trims availability of commodity SSDs for PCs and makes shortages the norm.
Volume and price are diverging. TSR associate director Kengo Ota estimates that enterprise SSD pricing per gigabyte will be 1.8x the PC segment in 2026, widening from 1.4x in 2025. The Q3 increase of about 20%, however, has narrowed from roughly 60% in the second quarter.
Passive components are following. Samsung Electro-Mechanics disclosed on 6 October an AI-server MLCC supply contract worth about KRW 285.6bn with a major global customer, covering the whole of 2027.
For buyers, allocation priority for high-capacity storage continues to rise, and long-term agreement terms and lead times are becoming the decisive variables.
YANGSHIN Technology distributes JC Semiconductor, Kangying Semiconductor and Youcun Technology memory and passive component lines.
Memory & Passive Component Distribution
For quotations and lead-time support, please contact the YANGSHIN Technology sales team at sales@yangshin.com