Our team of knowledgeable and experienced professionals can help our customers grasp the global electronic components market, provide you with the most relevant and practical perspective, so that you can understand the overall situation, and assist you to formulate the ideal design procurement strategy.
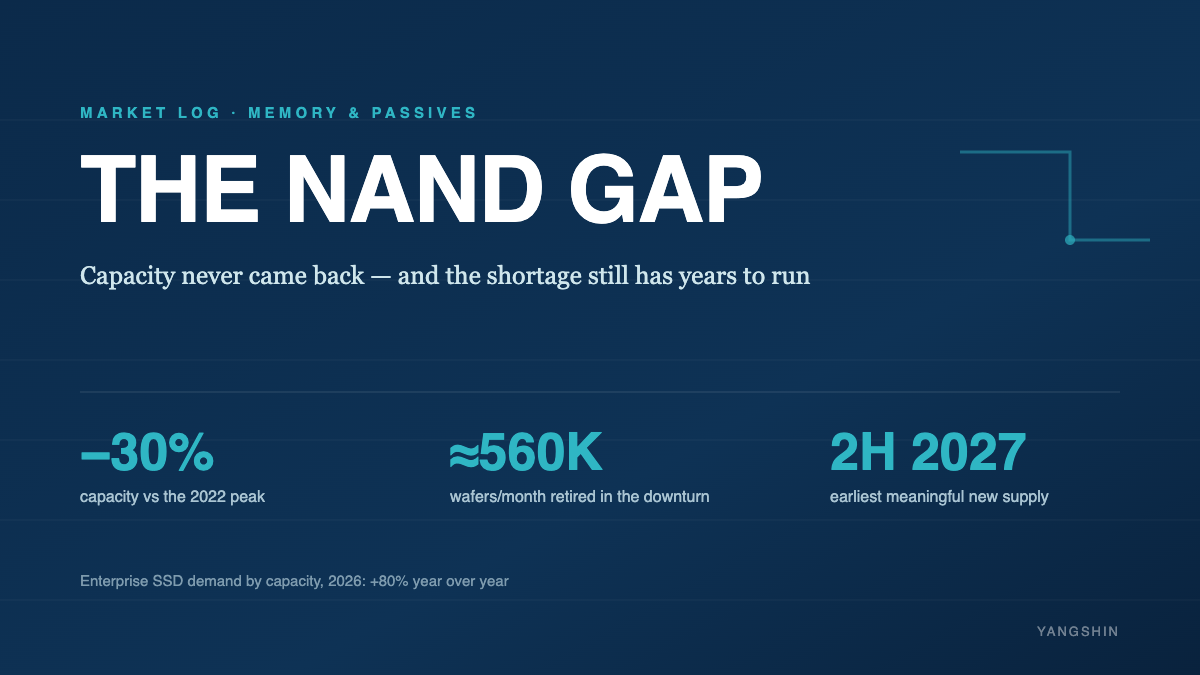
SanDisk says its NAND capacity is still about 30% below the 2022 peak, after retiring roughly 560,000 wafers per month. SK hynix is sold out on NAND through the end of 2026; more than 75% of Micron's fiscal 2027 output is already committed. TrendForce forecasts a further 15–20% rise in Q4 NAND contract prices, and 23–28% for enterprise SSDs.
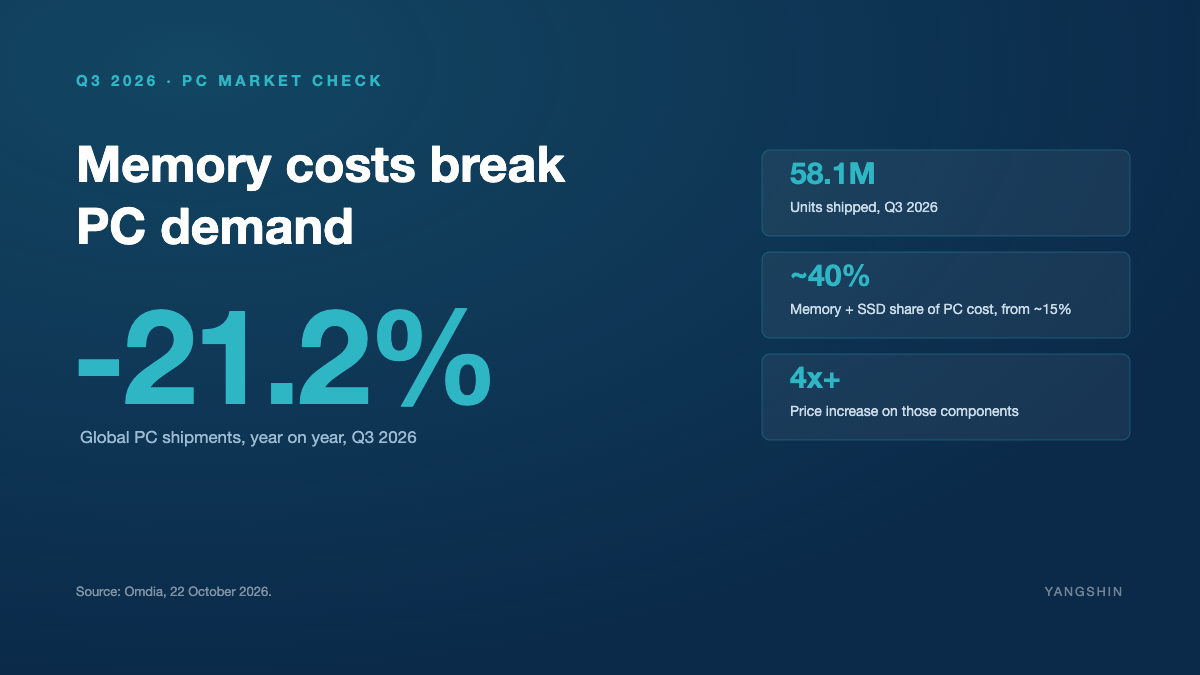
1. Omdia (22 Oct): Q3 2026 global PC shipments fell 21.2% YoY to 58.1 million units, the steepest drop since Q1 2023; Counterpoint puts the decline at about 21% and Gartner at 22.4%.
2. Omdia: DRAM and SSDs now account for close to 40% of PC bill-of-materials cost, up from roughly 15%, with those components more than four times dearer; OEM price rises have not fully offset it.
3. TrendForce spot prices on 22 Oct: DDR5 16Gb +0.38%, DDR4 8Gb +0.46%, DDR3 4Gb +0.66%, DDR4 16Gb flat - weaker demand has not reversed pricing.
4. Omdia forecasts a 24% decline in Q4 2026 and a further 7% in 2027 (forecast); MLCC makers have raised AI-server high-capacitance prices by 15%-35%.
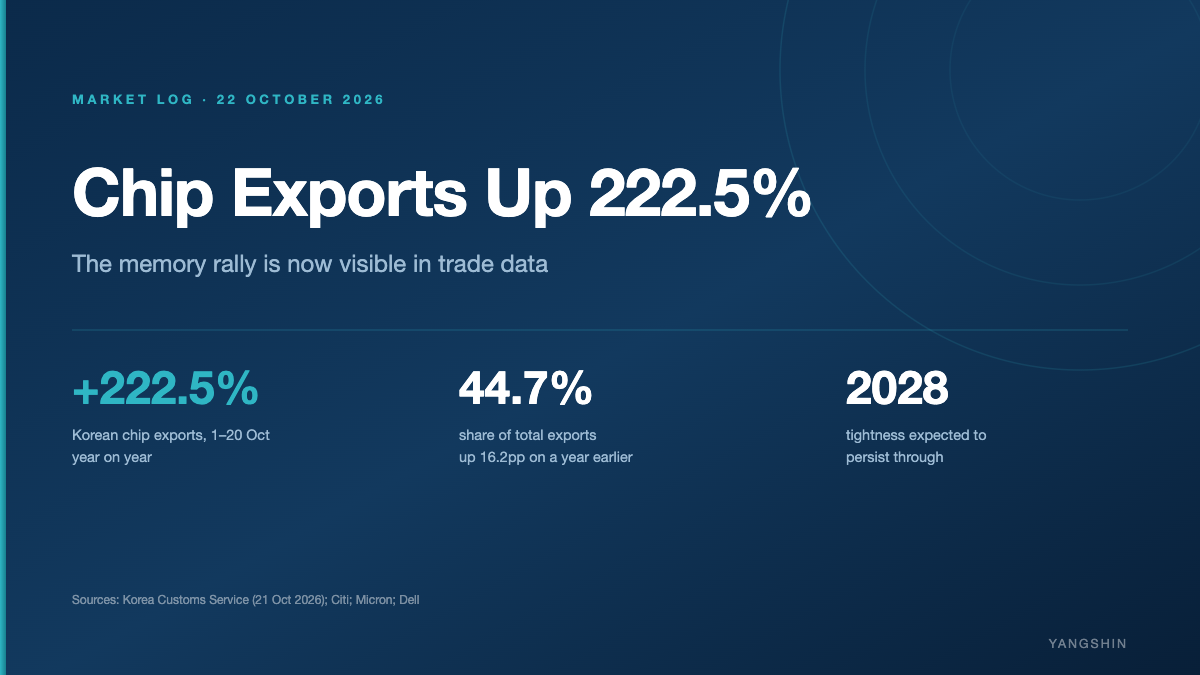
Korea Customs Service (21 Oct): chip exports for 1-20 October rose 222.5% year on year and took a 44.7% share of total exports, up 16.2 percentage points. Citi estimates SK hynix Q3 DRAM ASP +28% QoQ and NAND +24%, with revenue +314% YoY. Citi expects tightness through 2028; Dell's CEO puts meaningful new memory capacity in 2029-2030. Meritz: Samsung Electro-Mechanics MLCC lead times now 52 weeks.
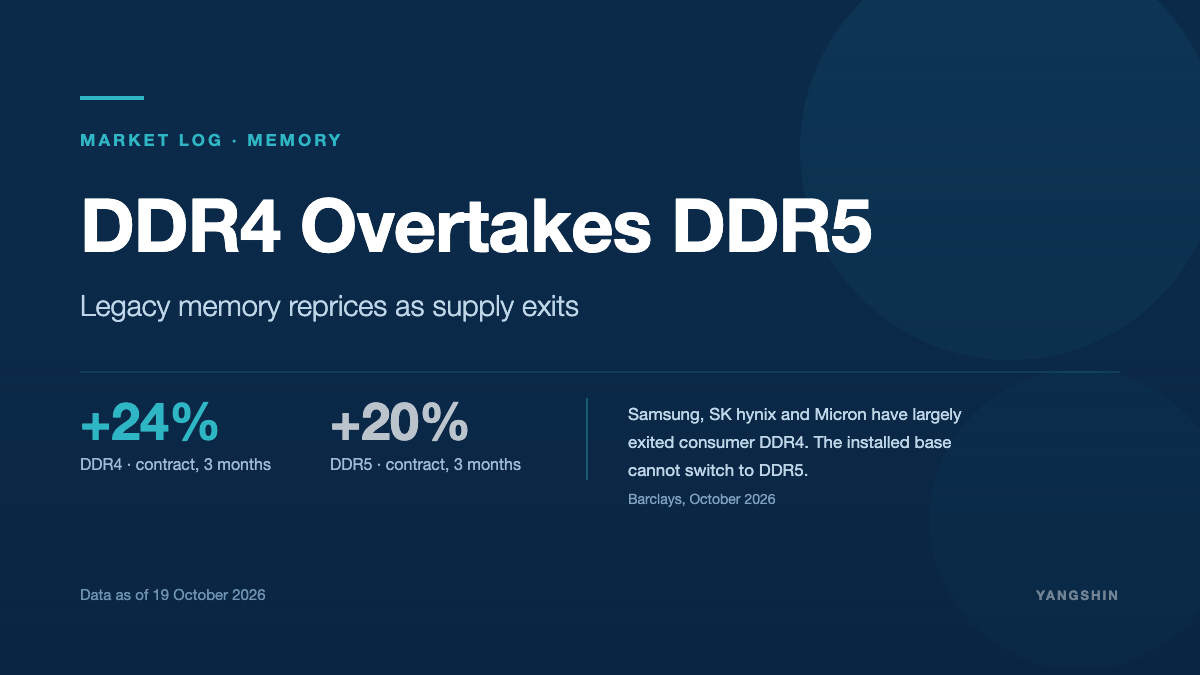
Barclays: DDR4 contract prices are up 24% over three months against 20% for DDR5 — the legacy generation now leads on momentum. Samsung, SK hynix and Micron have largely exited consumer DDR4, and the installed base cannot switch. New-customer agreements drop the price band and track spot.
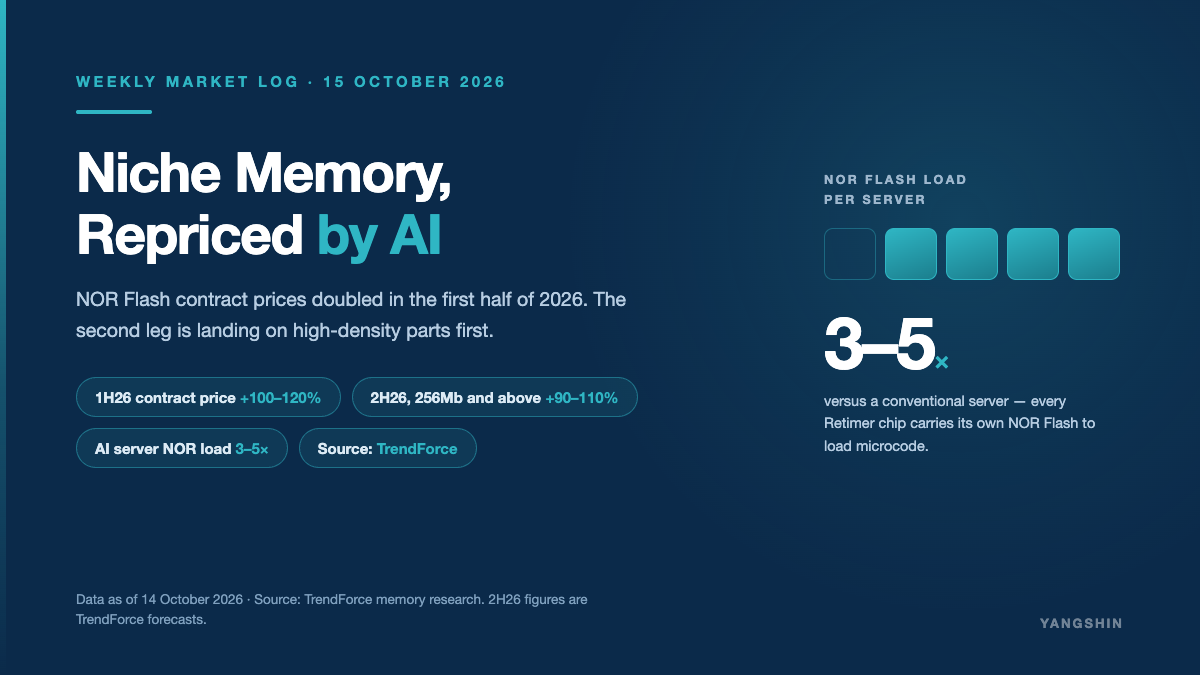
1. TrendForce data show NOR Flash contract prices rose 100-120% on average in the first half of 2026, the steepest cycle in nearly a decade.
2. The second half diverges: parts of 256Mb and above still have 90-110% to gain (TrendForce forecast), while 128Mb and below slow to 10-20% in 4Q26.
3. The demand shock comes from intensity, not unit volume: an AI server consumes 3-5 times as much NOR Flash as a conventional server, with 30+ NOR devices per rack, up from 3-5.
4. Supply is consolidating: Infineon agreed on 17 September 2026 to sell its NOR Flash and F-RAM business to Winbond for USD 1.12bn, with closing expected in 2H 2027.
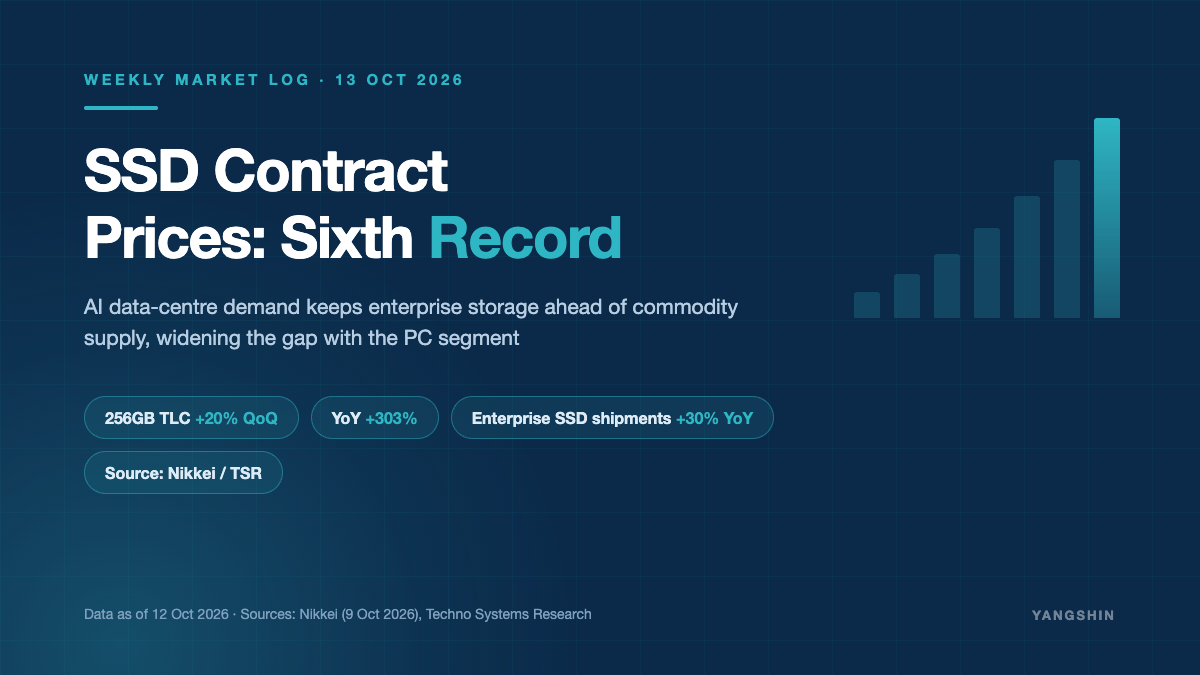
1. Nikkei (9 Oct): Q3 2026 contract prices settled at about USD 134.2 per 256GB TLC drive and USD 252.0 per 512GB drive, both up about 20% quarter on quarter - a sixth consecutive quarterly increase and a record high.
2. Year on year both are up 303% (256GB from USD 33.3, 512GB from USD 62.4); the Q3 rise of about 20% has narrowed from roughly 60% in Q2.
3. Techno Systems Research expects enterprise SSD shipments of 73.62 million units in 2026, up about 30% year on year; enterprise price per gigabyte is 1.8x the PC segment, up from 1.4x in 2025.
4. Passive components are following: Samsung Electro-Mechanics disclosed on 6 October an AI-server MLCC supply contract worth about KRW 285.6bn, covering the whole of 2027.
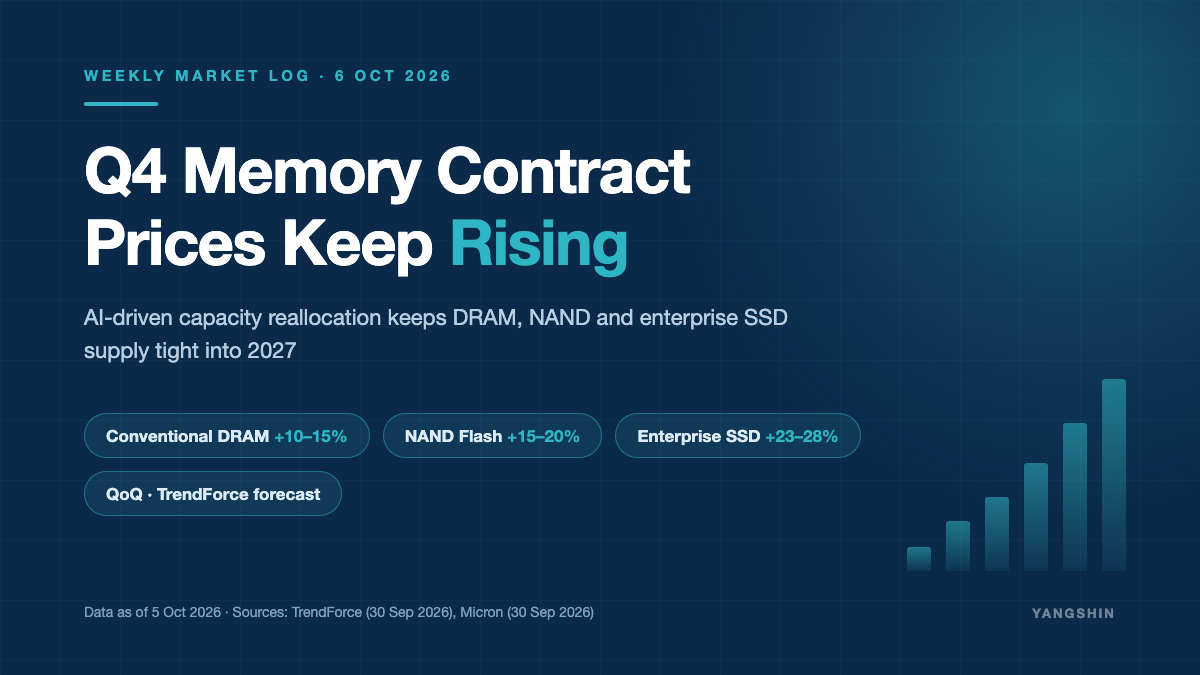
TrendForce forecasts Q4 contract prices up 10–15% for conventional DRAM, 15–20% for NAND and 23–28% for enterprise SSDs. Micron reported fiscal Q4 revenue of $54.23bn, up 379% year on year. The 2027 HBM4 quote from Samsung is about three times the per-gigabit price of current HBM3E, with suppliers expecting tighter supply in 2027.
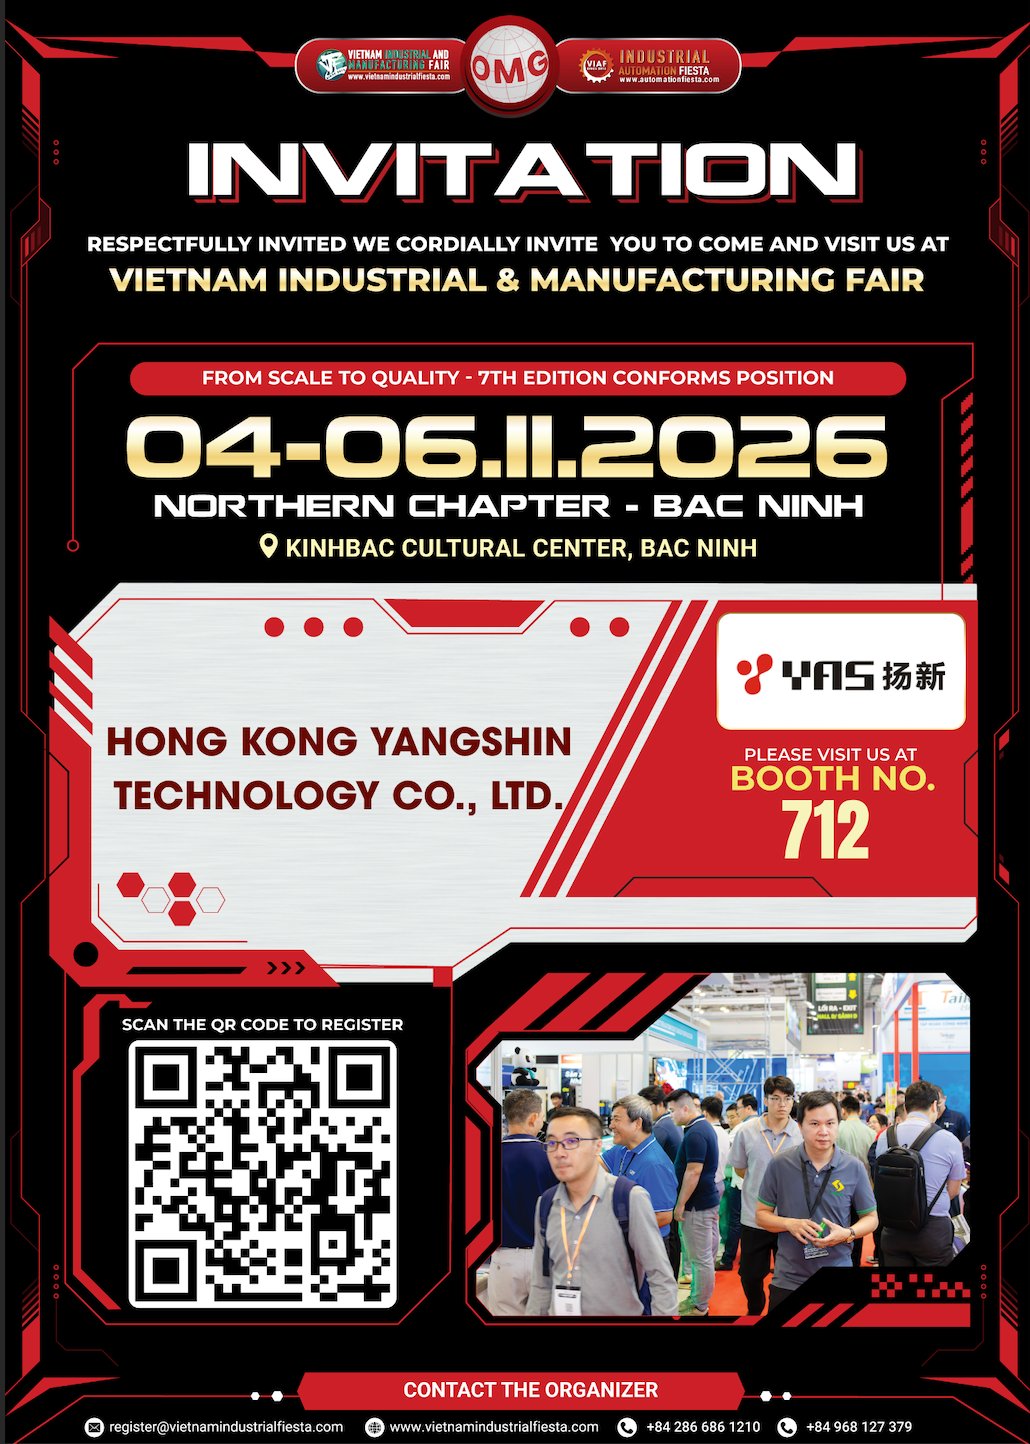
Yangshin (YAS) will exhibit at the Vietnam Industrial & Manufacturing Fair in Bac Ninh, Vietnam from 4 to 6 November 2026. Visit us at Booth No. 712.
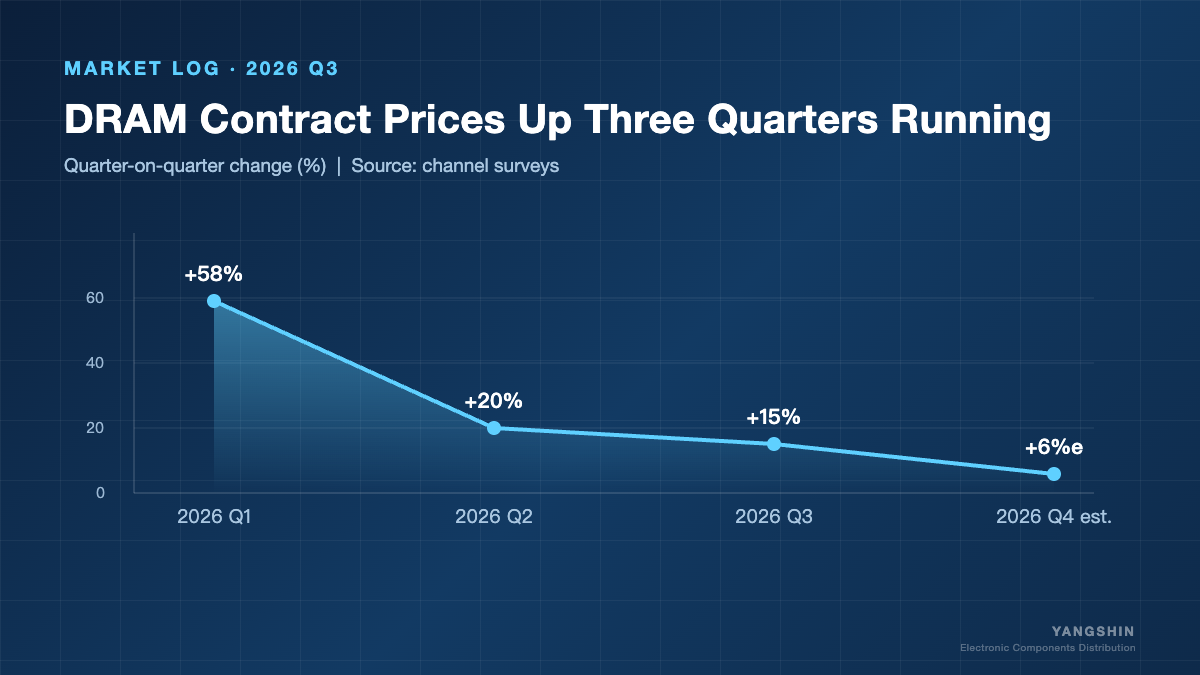
According to the latest channel survey, several hyperscale cloud providers have signed new agreements with memory manufacturers, accepting DRAM procurement prices for Q1 2027 above Q4 2026 levels. It is the first time in this upcycle that buyers have proactively accepted higher pricing and locked in forward contracts.
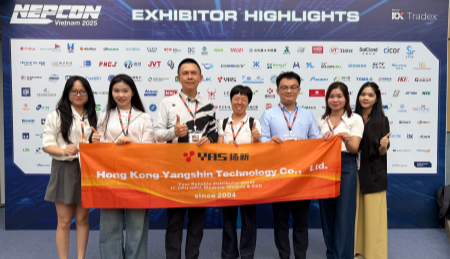
Yangshin showcases innovative technology at the 2025 Hanoi Electronics Show, exploring new manufacturing opportunities together** As a pioneer in the field of electronic manufacturing, Yangshin Technology made its debut at NEPCON Vietnam 2025 * (Hanoi Electronics Industry Exhibition) from September 10th to 12th
HongKong Yangshin Technology Co., Ltd. is pleased to announce its participation in the ENEPCON Vitnam-2025 exhibition hall (located at Hall 1, Booth L04, I.C.E. Hanoi, Vietnam), which will be held from September 10th to 12th, 2025. We are delighted to meet you at our booth and discuss the latest trends and opportunities for cooperation in the field of electronic components!
From November 12 to November 15 this year, YANGSHIN, a leader in the field of electronic components in Asia, participated in the Munich Electronics Show in Germany. YANGSHIN Technology attracted the attention of many industry professionals at the show. This event is an important international platform that provides companies with opportunities to connect with global buyers and partners.
On November 12, 2024, as the global technology industry focused on this historic city, the biennial electronica 2024 in Munich, Germany, grandly opened. As the world's leading electronics industry trade exhibition, electronica has been leading the forefront trends of all technologies, products, and solutions in the entire electronics industry for 60 years, reflecting the rapid development level of electronic technology in various fields.
According to foreign media reports, SK Hynix Semiconductor Inc. announced on March 31, 2023 the closure of its Italian and European research and development center in Agrate Brianza, a suburb of Milan, and will lay off a total of 39 local employees from the center, and has begun the firing process.
In 2022, SK Hynix Italy Srl, a South Korean semiconductor company, had a revenue of $34 billion and a net profit of $1.7 billion.
It is reported that the end of the Italian R&D center and the complete layoffs are mainly due to a technology gap between the Italian company and the Korean headquarters, but due to restrictions in Korean regulations and the company's inability to carry out technology transfers that require significant investment.
Talking about the "core" opportunities arising from the new development of intelligent networked vehicles