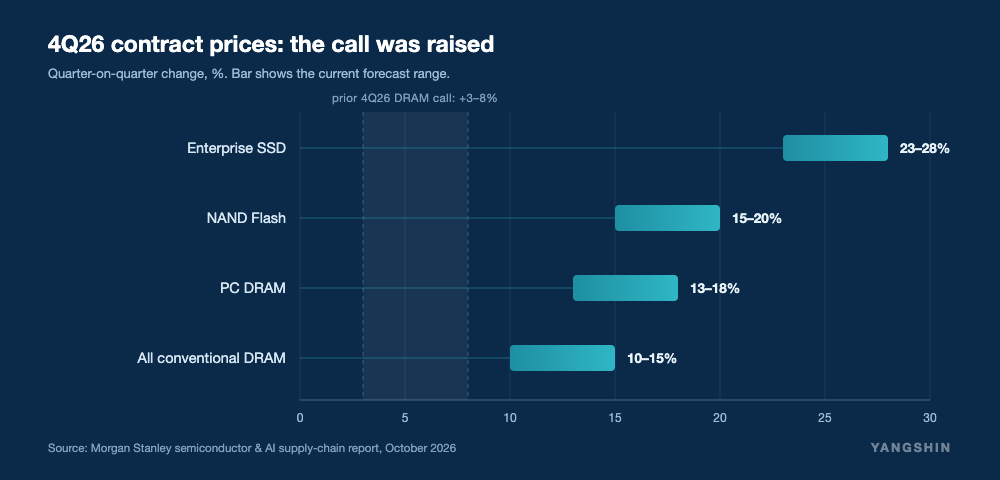
This memory upcycle is not a blanket shortage. Morgan Stanley's mid-October semiconductor and AI supply-chain report lifted its 4Q26 contract outlook across the board: DRAM from +3–8% to +10–15% quarter on quarter, NAND from 0–5% to +15–20%, and enterprise SSD to +23–28%, the steepest of any segment. In the same week, spot pricing pointed the other way.
Supply explains which segment is genuinely short. Fabs are steering leading-edge capacity to server DRAM and HBM, and NAND bits are being allocated to enterprise orders first. Morgan Stanley estimates DRAM capital spending at roughly USD 98 billion in 2026, rising to USD 150–160 billion in 2027, but most of it is absorbed by HBM4 lines, advanced packaging and cleanroom build-out; meaningful incremental bit supply is not expected before the second half of 2027.
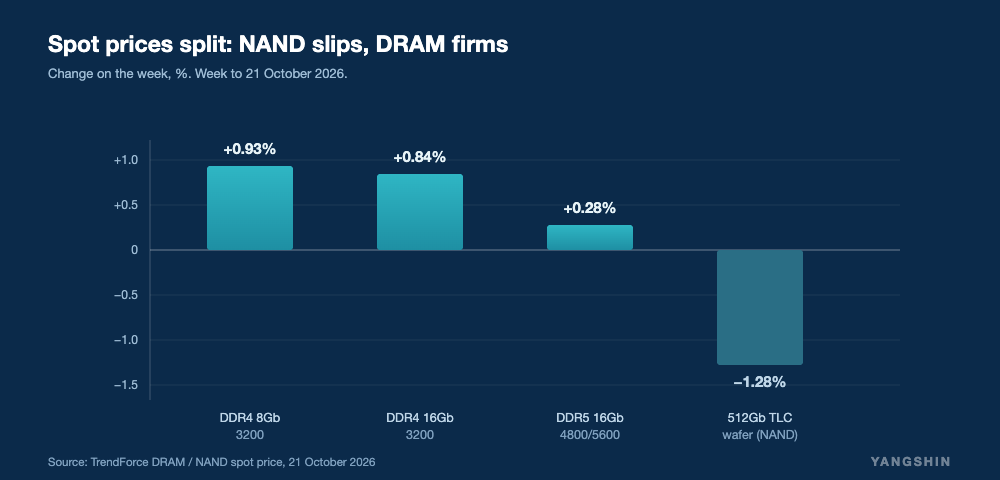
The evidence for the split sits in spot pricing. TrendForce data for 21 October show 512Gb TLC wafer down 1.28% on the week on soft module demand and elevated inventories, while DDR4 16Gb die rose 0.84% and DDR5 16Gb added 0.28%. The mix is shifting as well: QLC is forecast to move from 18% of enterprise SSD capacity in 2026 to 38% in 2027, at roughly one-third the cost of TLC for the same capacity. Enterprise and high-capacity parts are tight; consumer modules are not.
Lead time is becoming the binding constraint before price is. Korea's Herald Business reported on 20 October that Samsung Electro-Mechanics MLCC lead times have stretched to 52 weeks, meaning an order placed today ships a year out; its component division ran at 91% utilisation in the first half and its Philippine plant will not reach mass production until 2027. Quoted price is no longer the only variable; whether a scheduling slot can be secured matters just as much.
For buyers, the practical response is to tier by segment: secure first-half 2027 capacity for enterprise SSD and high-capacity QLC modules, confirm scheduling slots early for high-capacitance MLCC, and wait for bundling windows on consumer NAND. YANGSHIN Technology distributes memory and passive component lines from JC Semiconductor, Kangying Semiconductor and Youcun Technology.
Memory & Passive Component Distribution
For quotations and lead-time support, please contact the YANGSHIN Technology sales team at sales@yangshin.com